Broadcom vs. Nvidia: 3 Key Metrics Point to the Stronger AI Chipmaker to Buy After Earnings
Nvidia (NVDA -0.03%) and Broadcom, two of the largest chipmakers in the world, have now both reported earnings for their most recent quarters, which ended at the end of July for Nvidia, and in early August for Broadcom.
Both put up strong results as well. Nvidia’s adjusted revenue grew 106% year over year, while diluted earnings per share (EPS) rocketed 120%. Meanwhile, Broadcom had adjusted net revenue growth of 86% and adjusted diluted EPS growth of 96%.
Both companies also topped Wall Street average estimates as well.
Although there is an investment case to be made for Nvidia and Broadcom, three key metrics point to the stronger AI chip stock following their respective earnings reports.
Image source: Getty Images.
1. Nvidia and Broadcom both stunned with guidance
One of the first metrics in earnings reports that Wall Street analysts and investors look at is forward financial guidance, which both Nvidia and Broadcom provide to some extent. Specifically, they are looking to see how company forecasts compare to Wall Street estimates.
Broadcom projected revenue of $34.8 billion in its current quarter, slightly below analyst estimates of $35.03 billion.
However, on its earnings call, Chief Executive Officer Hock Tan said it believes its AI semiconductor revenue is set to double in 2027 to $115 billion and then double again in 2028 to $230 billion, with 2028 guidance coming in $50 billion ahead of analyst estimates.
While that’s quite impressive, it will likely be difficult for analysts to get comfortable with the 2028 outlook just yet.
Nvidia, as it typically does, also knocked it out of the park with its guidance. The company forecast revenue of $108 billion in the current quarter, roughly $2.5 billion above estimates.
The company also projected 70% annual revenue growth in fiscal year 2028, with most of that occurring in calendar year 2027, while analysts had only estimated 44%. Not only did that beat forecasts, but it’s also incredible growth given the company’s $5 trillion-plus market cap.
2. Gross margins
Another metric investors closely watch for both Nvidia and Broadcom is gross margin, the percentage of revenue remaining after accounting for the cost of goods sold, which includes labor, materials, and overhead.
Gross margin shows how much a company makes from each sale before paying for other business costs, such as fixed costs, debt, or taxes. Gross margin is also representative of pricing power.
In its second quarter of fiscal 2027, Nvidia continued to boast gross margins of roughly 75%. However, this figure is expected to slip, with Nvidia predicting a 74% gross margin in the current quarter, followed by further contraction as the fiscal year progresses.
In fact, Nvidia expects its gross margins to narrow to the 71% to 72% range, the point at which management expects gross margins to inflect higher. Management attributed the margin contraction to higher memory costs.
In its most recent quarter, Broadcom had a consolidated gross margin of 75%. Management anticipates the current quarter gross margin will slip to 73%, as the company sells more of its custom chips, which are more memory-intensive.
However, Broadcom’s management team has told analysts not to focus on gross margin, as it believes operating margin better reflects its business.
3. More attractive entry point
Finally, following earnings, Nvidia still trades at a cheaper forward earnings multiple than Broadcom.
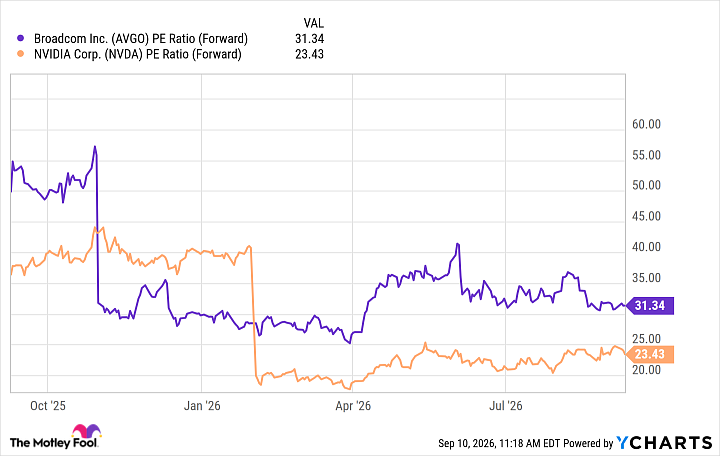
AVGO PE Ratio (Forward) data by YCharts
Now, this could be because Broadcom expects faster AI growth in 2027 and likely in 2028 as well.
Ultimately, I still find Nvidia to be the more attractive play here. Sure, its growth may not be as fast, but it’s still calling for 70% revenue growth at a market cap roughly three times Broadcom’s. Nvidia generated $89 billion in AI chip revenue last quarter, compared with Broadcom’s nearly $21 billion.
Investors have never seen growth like this at a company with Nvidia’s scale. I also think Nvidia’s fast-growing central processing unit (CPU) business is something for investors to be excited about.