Are These Three TSX Value Stocks (TSX:OGC) Undervalued Now?
Highlights
- Rising borrowing costs are pushing investors toward proven cash generating businesses.
- Three Canadian companies are screening as undervalued on cash flow basis.
- Mining, accessibility equipment and energy sectors all appear in this list.
Three Canadian companies, spanning mining, accessibility equipment, and integrated energy, are drawing attention as cash flow focused value candidates amid a higher interest rate backdrop.
Higher long-term interest rates have put greater emphasis on cash flow, as elevated borrowing costs and tighter credit conditions leave less room for businesses that rely heavily on future growth expectations. For Canadian investors, this environment has increased attention on companies generating meaningful cash from established operations while trading at comparatively modest valuations. OceanaGold
(TSX:OGC)
OceanaGold Corporation (TSX:OGC)
39.79
CAD
+0.560
1.428%
Last Updated at: 2026-09-22T16:36:00Z
stands out in this context, with its producing assets and operating profile placing the Vancouver-based miner among the companies currently screening as undervalued on a cash-flow basis within the TSX Smallcap Index.
Why Cash Flow Matters More Now?
When borrowing becomes more expensive, the market tends to place a premium on businesses that are already converting operations into real, measurable cash rather than relying on future financing to bridge the gap. That backdrop has made cash flow based screening a more prominent tool for identifying names that may be overlooked relative to their underlying earning power. It has also placed renewed focus on sectors like TSX Metal & Mining Stocks, where operating assets generate steady revenue streams regardless of where sentiment sits on any given day.
OceanaGold’s Producing Asset Base
OceanaGold
(TSX:OGC)
OceanaGold Corporation (TSX:OGC)
39.79
CAD
+0.560
1.428%
Last Updated at: 2026-09-22T16:36:00Z
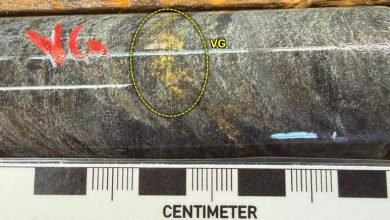
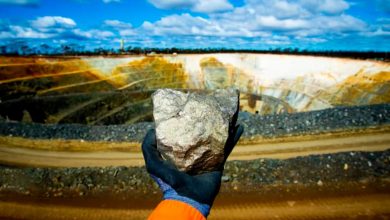
explores, develops and operates a portfolio of gold and copper mines, and its relevance to this cash flow theme comes down to one simple fact: its producing assets are already generating hard, measurable cash today rather than depending on projects still years away from output. Revenue flows in from several operating mines spread across different regions, giving the business a degree of diversification within its core mining operations. Plans are also underway to optimize output at one of its key assets, restoring normal underground production rates and working toward a higher annual mining target, a move aimed at lifting both copper and gold output from what is already considered a lower cost operation. The intent behind that push is straightforward: strengthen consolidated cash flow and margins over time. What ultimately determines how much of that potential gets realized may hinge on cost pressures that rarely show up clearly in headline production numbers, making this a name worth continued attention within the broader materials category.
Savaria’s Recurring Service Model
The second name worth examining is Savaria
(TSX:SIS)
29.67
CAD
+0.430
1.471%
Last Updated at: 2026-09-22T16:35:00Z
, a company that designs, manufactures and installs accessibility equipment and adapted vehicles, generating recurring installation, retrofit and service driven cash flows rather than depending purely on one time equipment sales. The bulk of its revenue comes from accessibility and adapted vehicle offerings, with a smaller but meaningful contribution from patient care related operations spread across Canada, the United States and Europe. What makes Savaria particularly relevant to this undervalued cash flow theme is its ability to convert hardware sales into steady, service backed income over time, a model that tends to smooth out revenue compared with businesses reliant purely on upfront transactions.
Broader demographic trends are frequently cited as a tailwind for this kind of business, since an aging population combined with increasing urban density is expected to lift demand for home accessibility solutions such as stairlifts and home elevators. Whether future cash returns actually accelerate may come down to a quieter factor, how the economics of each individual installation project pay back their upfront cost over time, a detail that matters more to long term margins than headline revenue figures suggest.
Suncor’s Integrated Cash Engine
The third name on this list operates at a considerably larger scale. Suncor Energy
(TSX:SU)
95.48
CAD
+0.990
1.048%
Last Updated at: 2026-09-22T16:44:00Z
, part of the broader TSX Energy Stocks category, is an integrated Canadian energy company that produces bitumen from oil sands operations and processes crude into refined fuels for end customers. Its relevance to this cash flow theme stems from the sheer scale of its operations, with long lived oil sands assets feeding a sizable and consistent cash engine. Revenue is generated across oil sands production, refining and marketing, and exploration and production segments, giving the business multiple points of cash generation rather than dependence on a single revenue stream.
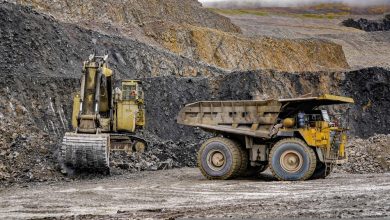
Recent efficiency initiatives, including automated haul systems, upgraded haul roads and incremental improvements at refining operations, have already delivered meaningful gains from the same underlying asset base. The open question going forward is whether comparable step changes can be repeated at a similar pace, since finding the next round of productivity gains often grows more difficult once the easier improvements have already been captured. That dynamic could place pressure on future margins if throughput gains slow while costs continue climbing, a tension worth watching closely for anyone following this integrated energy operator.
What Ties These Three Names Together
Despite operating in entirely different corners of the Canadian economy, mining, accessibility equipment, and integrated energy, all three companies share a common thread: each generates substantial cash from established, operating assets rather than relying heavily on speculative future projects. That distinction matters considerably in a higher rate environment, where the market has grown less forgiving of businesses whose value stocks depends primarily on distant promises rather than current cash generation.
At the same time, each name carries its own set of considerations. Mining operations remain sensitive to commodity price swings and operational execution. Accessibility equipment businesses depend on how efficiently individual projects convert into recurring service revenue. Integrated energy operations face the ongoing challenge of sustaining productivity gains once the more obvious efficiency wins have already been captured. None of these factors guarantee any particular outcome, but they do help explain why each business continues to draw attention from investors focused on cash flow based screening approaches.
A Broader Starting Point, Not A Finish Line
These three names represent a starting point rather than a complete picture of where value may currently exist across the Canadian market. Cash flow based screening tends to surface a wider range of candidates than any single article can reasonably cover, and each name deserves its own closer look at balance sheet strength, competitive positioning, and the specific risks tied to its industry before drawing firm conclusions.