Global’s September 2026 Stocks That May Be Trading Below Estimated Fair Value
As global markets navigate the complexities of rate hikes, fluctuating oil prices, and geopolitical tensions, investors are increasingly focused on identifying opportunities that may be trading below their estimated fair value. In this environment of mixed index performances and sector-specific volatility, discerning stocks with strong fundamentals and potential for appreciation can be a prudent strategy for long-term growth.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Storytel (OM:STORY B) | SEK115.30 | SEK230.44 | 50% |
| Rakus (TSE:3923) | ¥1077.50 | ¥2065.35 | 47.8% |
| Promotica (BIT:PMT) | €3.00 | €5.75 | 47.8% |
| PAL GROUP Holdings (TSE:2726) | ¥1471.00 | ¥2890.01 | 49.1% |
| KSB SE KGaA (XTRA:KSB) | €880.00 | €1758.24 | 49.9% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €12.06 | €23.14 | 47.9% |
| Kingnet Network (SZSE:002517) | CN¥16.18 | CN¥31.45 | 48.5% |
| Double Medical Technology (SZSE:002901) | CN¥41.46 | CN¥79.66 | 48% |
| Apator (WSE:APT) | PLN24.95 | PLN48.76 | 48.8% |
| AK Medical Holdings (SEHK:1789) | HK$4.905 | HK$9.53 | 48.5% |
Let’s take a closer look at a couple of our picks from the screened companies.
Overview: Storytel AB (publ) operates in the audiobook and publishing market across several countries including Sweden, Denmark, and the United States, with a market cap of approximately SEK8.92 billion.
Operations: The company’s revenue segments include Publishing, which generated SEK1.33 billion, and Segment Adjustment, contributing SEK3.60 billion.
Estimated Discount To Fair Value: 50%
Storytel is trading significantly below its estimated future cash flow value, with a share price of SEK 115.3 compared to an estimated value of SEK 230.44, making it undervalued based on cash flows. The company’s earnings have shown robust growth, increasing by a very large margin over the past year, and are forecast to grow faster than the Swedish market. Recent share repurchase initiatives aim to optimize capital structure and enhance shareholder value.
Overview: Vector Inc. operates in the public relations and advertising sectors across Japan, China, and internationally, with a market capitalization of approximately ¥93.06 billion.
Operations: The company’s revenue is primarily derived from PR and Advertising at ¥35.97 billion, followed by Direct Marketing at ¥17.16 billion, Press Release Distribution at ¥9.77 billion, HR services at ¥2.54 billion, and Investment activities contributing ¥719 million.
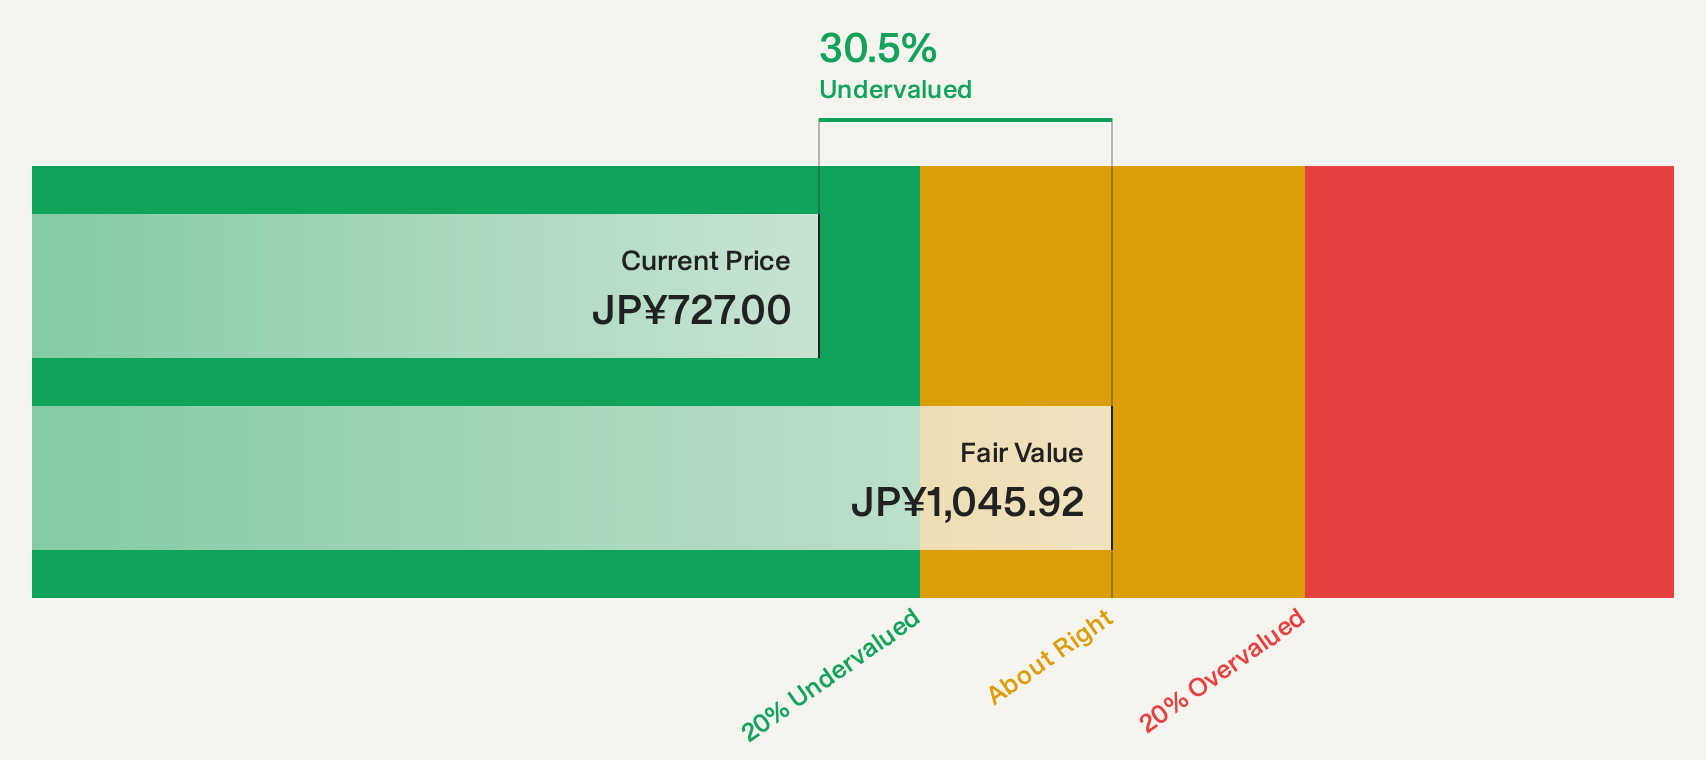
Estimated Discount To Fair Value: 38.1%
Vector is trading significantly below its estimated future cash flow value, with a share price of ¥1,929 compared to an estimated value of ¥3,117.95. The company recently raised earnings guidance for the first half of fiscal 2026 due to higher-than-expected profits in its Direct Marketing and Investment segments. Despite high volatility in recent months, Vector’s earnings are forecast to grow annually by 10.2%, outpacing the Japanese market’s growth rate.
Overview: Elan Corporation operates in the nursing care business primarily in Japan, with a market cap of ¥44.40 billion.
Operations: The company generates its revenue from the nursing care business primarily in Japan.
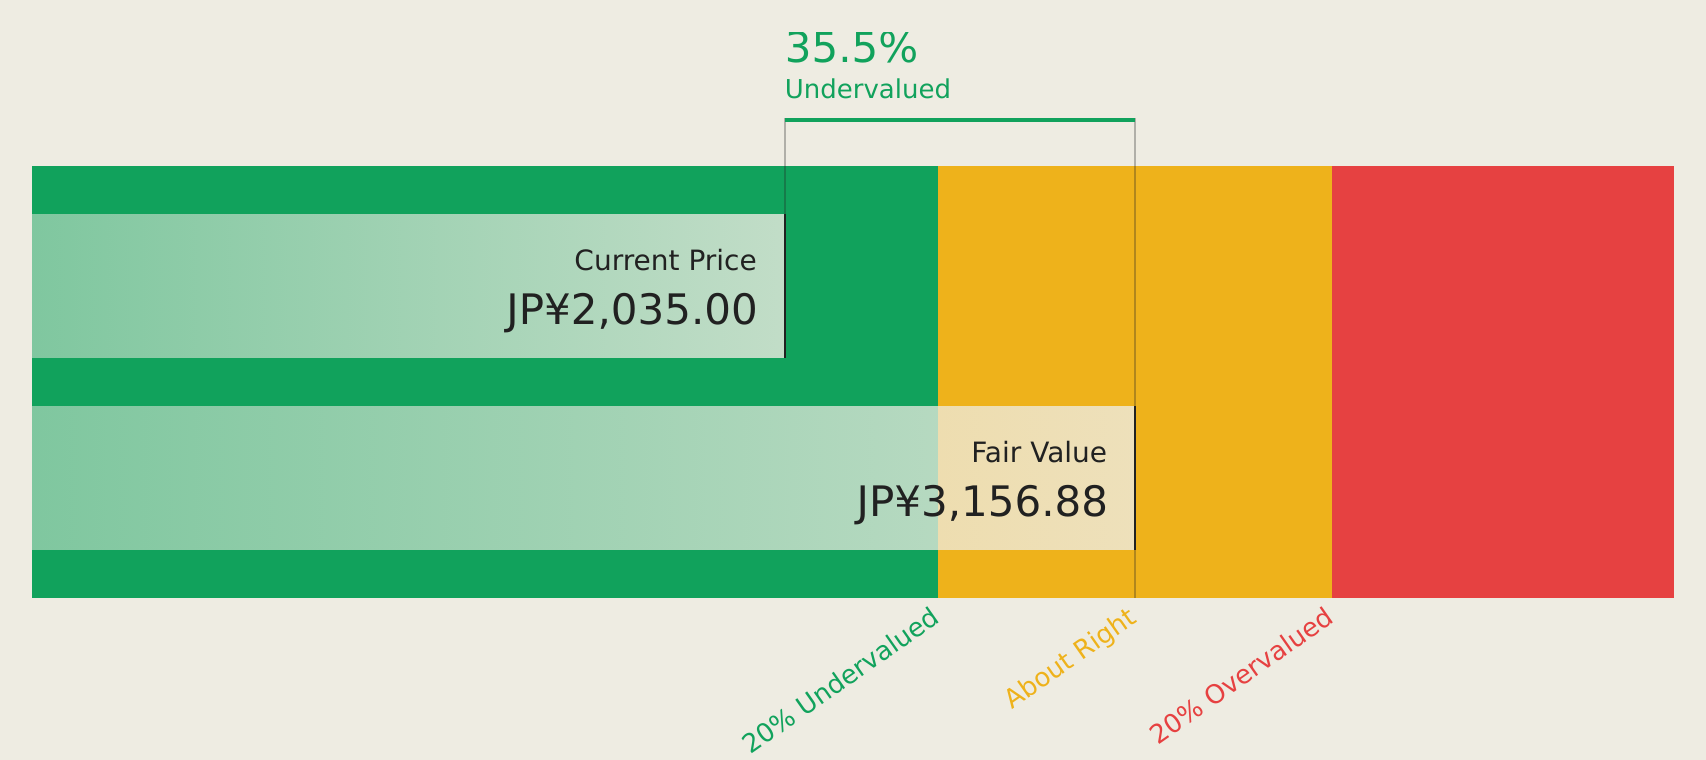
Estimated Discount To Fair Value: 30.5%
Elan is trading 30.5% below its estimated fair value, with a share price of ¥727 compared to an estimated future cash flow value of ¥1,045.92. The stock appears undervalued based on discounted cash flow analysis, and earnings are projected to grow annually by 9%, aligning with the broader market growth rate but outpacing the market’s revenue growth forecast of 6.4%. However, Elan’s return on equity is expected to remain modest at 19%.
Seize The Opportunity
Curious About Other Options?
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Elan might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com