Global Market’s 3 Stocks That Might Be Trading Below Fair Value Estimates
As global markets navigate a landscape marked by interest rate hikes from the Federal Reserve and the Bank of Japan, alongside volatile oil prices due to Middle East tensions, investors are keenly observing how these factors influence market indices. In such an environment, identifying stocks that may be trading below their fair value estimates can present opportunities for those looking to capitalize on potential market inefficiencies.
Top 10 Undervalued Stocks Based On Cash Flows
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| Rakus (TSE:3923) | ¥1082.00 | ¥2062.22 | 47.5% |
| PAL GROUP Holdings (TSE:2726) | ¥1486.00 | ¥2869.67 | 48.2% |
| Niterra (TSE:5334) | ¥7218.00 | ¥13807.45 | 47.7% |
| KSB SE KGaA (XTRA:KSB) | €892.00 | €1756.35 | 49.2% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €12.08 | €23.11 | 47.7% |
| Kingnet Network (SZSE:002517) | CN¥16.40 | CN¥31.44 | 47.8% |
| Cheil Worldwide (KOSE:A030000) | ₩17690.00 | ₩33788.53 | 47.6% |
| Apator (WSE:APT) | PLN25.30 | PLN48.80 | 48.2% |
| AK Medical Holdings (SEHK:1789) | HK$4.935 | HK$9.55 | 48.3% |
| 3SBio (SEHK:1530) | HK$16.77 | HK$32.14 | 47.8% |
Let’s dive into some prime choices out of the screener.
Overview: LG CNS Co., Ltd. is an IT service company operating in South Korea and internationally, with a market cap of ₩6.94 billion.
Operations: LG CNS generates revenue through its IT service operations both domestically in South Korea and on an international scale.
Estimated Discount To Fair Value: 21.7%
LG CNS is trading at a 21.7% discount to its estimated fair value, with shares priced below future cash flow valuations. Despite forecasted earnings growth of 9.6% annually, which is slower than the broader KR market, the company remains attractive due to its strong cash flow position and recent strategic alliances in quantum computing and AI infrastructure. The stock’s potential for price appreciation aligns with analyst expectations of a 42.9% increase in value.
Overview: Busy Ming Group Co., Ltd. operates as a food and beverage retailer in China with a market capitalization of HK$79.81 billion.
Operations: The company generates revenue primarily from its grocery store operations, amounting to CN¥83.04 billion.
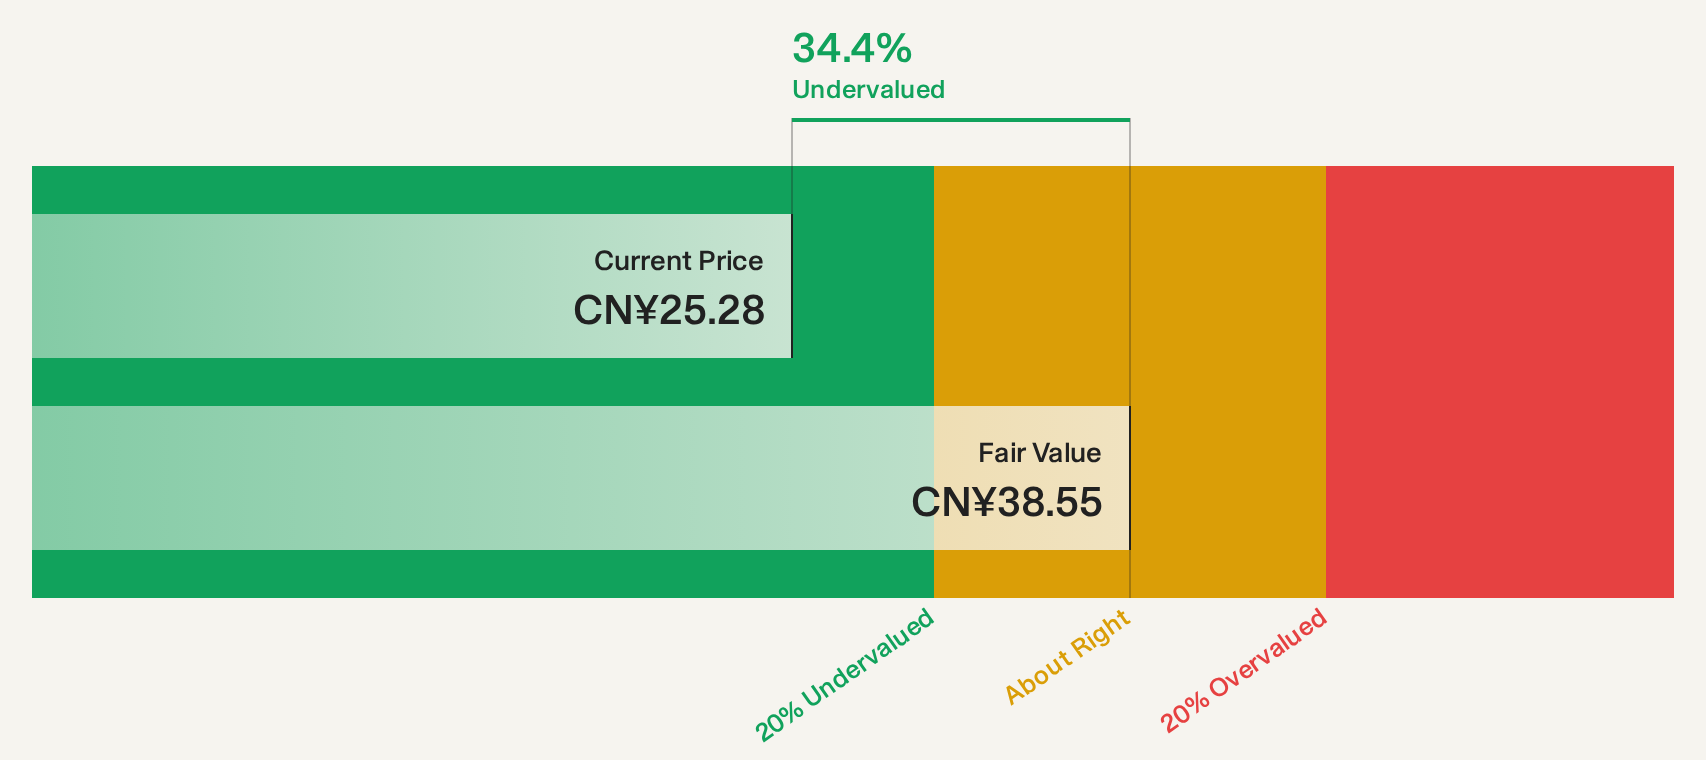
Estimated Discount To Fair Value: 43.2%
Busy Ming Group is trading at a significant discount to its estimated fair value, with shares priced below future cash flow valuations by over 20%. The company reported substantial earnings growth of 139.7% year-over-year, and its earnings are forecasted to grow significantly faster than the Hong Kong market. Despite revenue growth projections being slower than desired, Busy Ming’s strong profit outlook and current undervaluation present an appealing investment opportunity based on cash flows.
Overview: Yutong Bus Co., Ltd., along with its subsidiaries, manufactures and sells buses both in China and internationally, with a market cap of CN¥57.94 billion.
Operations: Yutong Bus Co., Ltd. generates its revenue primarily through the manufacturing and sale of buses within China and to international markets.
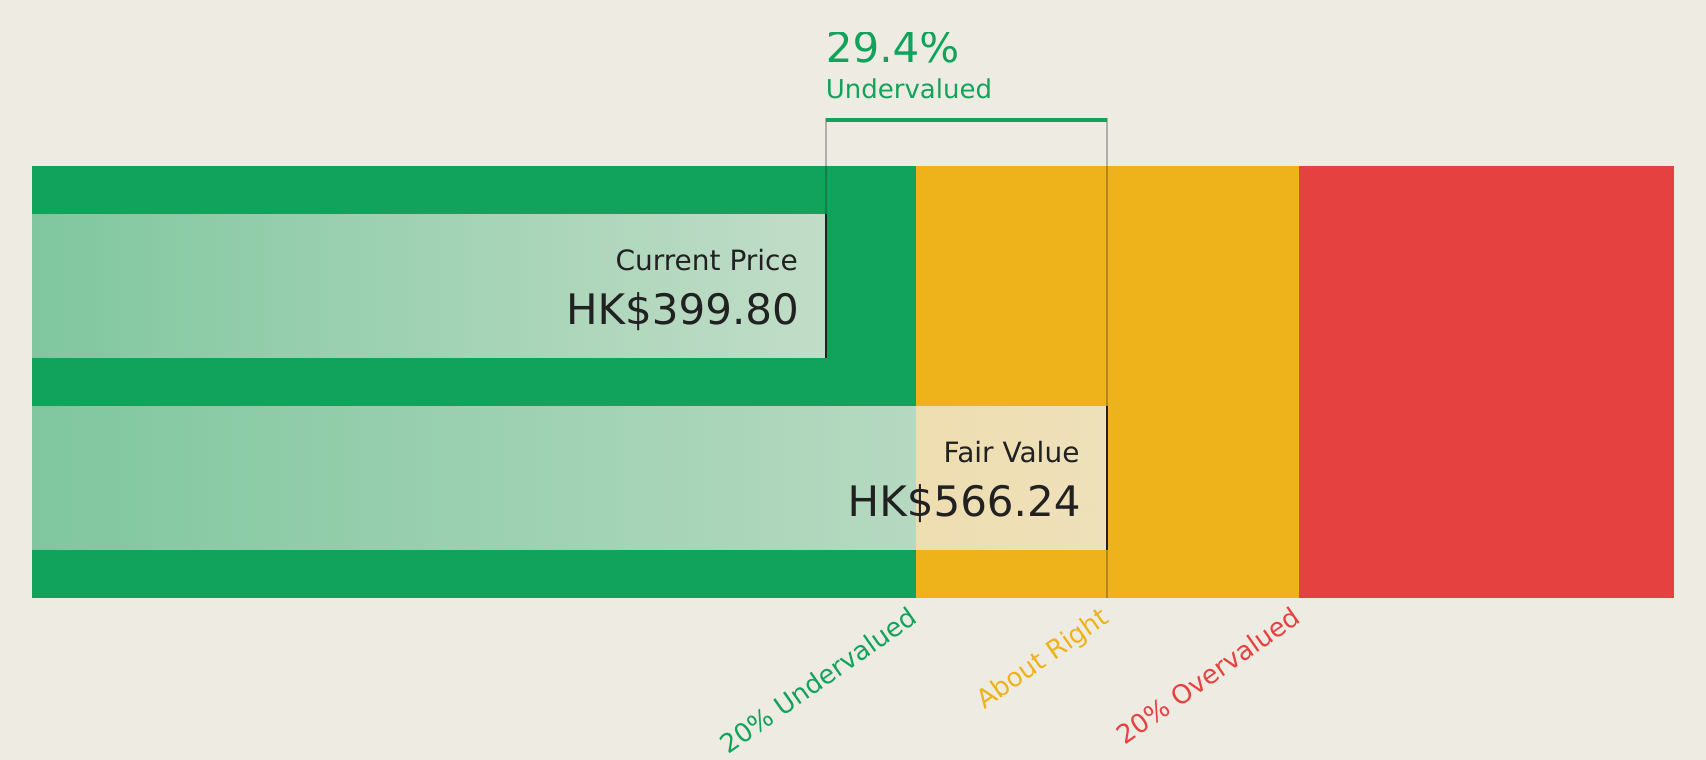
Estimated Discount To Fair Value: 34.4%
Yutong Bus Ltd. is trading 34.4% below its estimated fair value based on cash flow analysis, with a current price of CN¥25.28 compared to a future cash flow value of CN¥38.55. Despite earnings growth forecasted at 11.3% annually, slower than the Chinese market average, Yutong’s recent European expansion with its service center in Norway could enhance operational efficiency and customer support, potentially bolstering future cash flows and valuation prospects.
Next Steps
Ready For A Different Approach?
This article by Simply Wall St is general in nature. We provide commentary based on historical data
and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice.
It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your
financial situation. We aim to bring you long-term focused analysis driven by fundamental data.
Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material.
Simply Wall St has no position in any stocks mentioned.
Valuation is complex, but we’re here to simplify it.
Discover if Busy Ming Group might be undervalued or overvalued with our detailed analysis, featuring fair value estimates, potential risks, dividends, insider trades, and its financial condition.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com